POS & Payments
Nail Salon Credit Card Processing Fees Explained
Understand salon card processing statements by separating pricing structure, transaction charges, recurring fees and the effective rate for a defined period.
By Ontiloo · October 14, 2026 · 2 min read
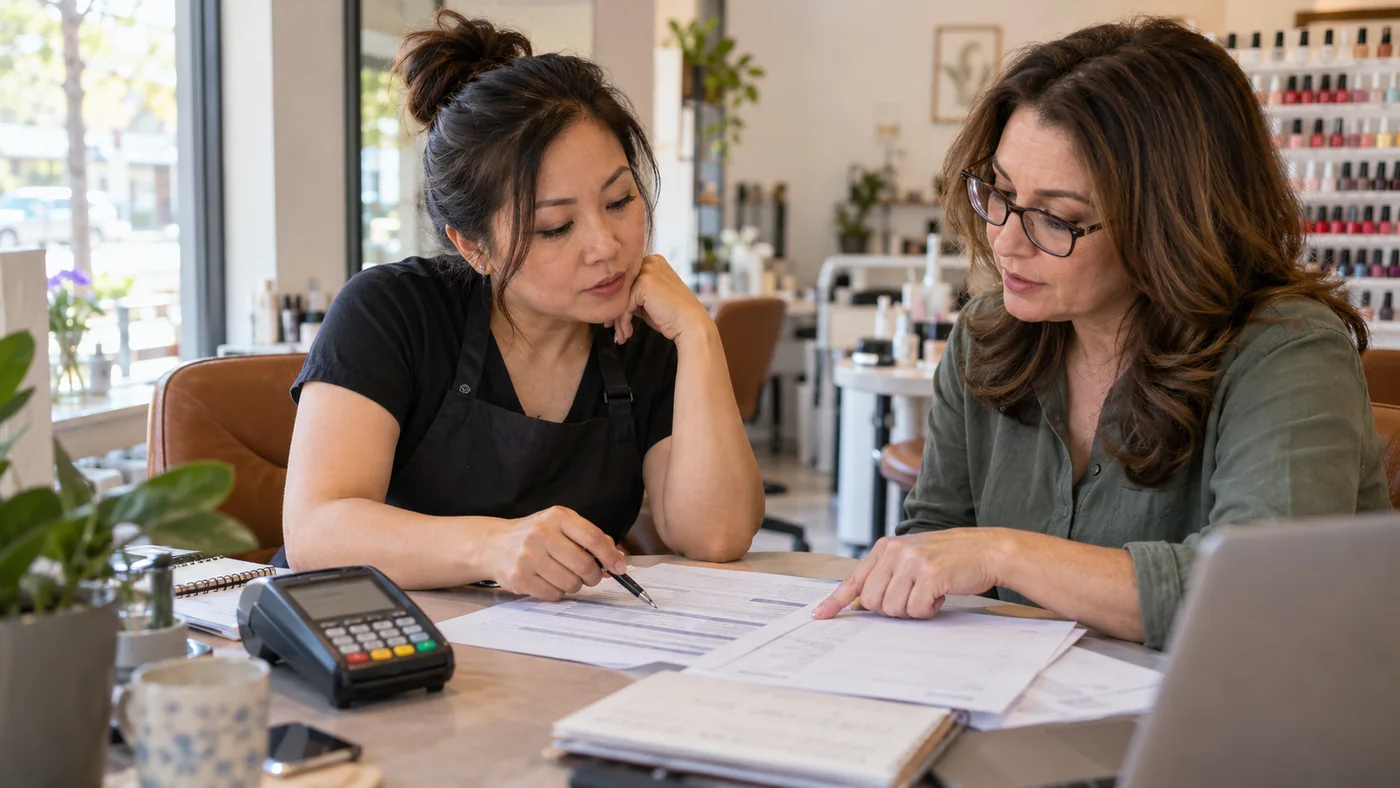
A card processing bill can contain several kinds of charges. To compare salon merchant services, identify the pricing structure, understand what each fee covers and calculate a consistent effective rate. A quoted percentage alone rarely describes the full monthly cost.
Separate the components
Payment processing can involve card-network and issuer-related costs, the provider’s pricing and additional service charges. How those appear depends on the agreement. Flat-rate, interchange-plus and tiered proposals present costs differently, so ask the provider to explain the actual schedule rather than relying on the label.
| Statement item | Question |
|---|---|
| Percentage-based charges | Which sales amount and transaction types do they apply to? |
| Per-transaction charges | Are authorizations, sales, refunds or other events charged separately? |
| Monthly fees | What service does each fee cover? |
| Equipment or software | Is it included in processing or billed elsewhere? |
| Adjustments and disputes | What event produced the charge and what terms apply? |
Calculate a comparable effective rate
Effective processing rate = included processing fees ÷ the matching processed card volume × 100. Define which fees and volume are included, and use the same definition each month. A settlement deposit is not automatically the correct denominator because it may already reflect fees, refunds or adjustments.
Illustrative example: $1,500 of defined processing fees on $50,000 of matching card sales produces a 3% effective rate. That number does not identify which provider component is negotiable, and it is not a quote or an industry benchmark.
Understand why months differ
Changes in average ticket, transaction count, card mix, keyed payments and refunds may affect the bill. Compare similar periods and annotate unusual events. If the rate changes, ask the provider to reconcile the difference with the agreement and transaction activity.
Use primary documentation for network concepts
Visa’s fees and rules resource explains interchange in the payment system and distinguishes it from the merchant’s negotiated charges. Your own agreement determines what the salon is billed.
Prepare for a cost review
Collect recent statements, the pricing schedule, equipment terms and a list of services included. Share them through an agreed secure channel and remove unnecessary customer data. Ask for a line-by-line explanation and a written comparison using your actual operating assumptions.
Keep exploring
Published by Ontiloo · October 14, 2026. Examples are illustrative unless stated otherwise. Product capabilities, prices and platform rules should be checked against the current provider documentation and your agreement.